In August, Bitcoin delivered a resounding slap to the faces of those predicting a summer slump.
Bitwise data shows that BTC rose approximately 25% in August, marking its third-best August performance in history, second only to 65.6% in 2017 and 30.7% in 2013. More importantly, this was the first positive August return since 2021.
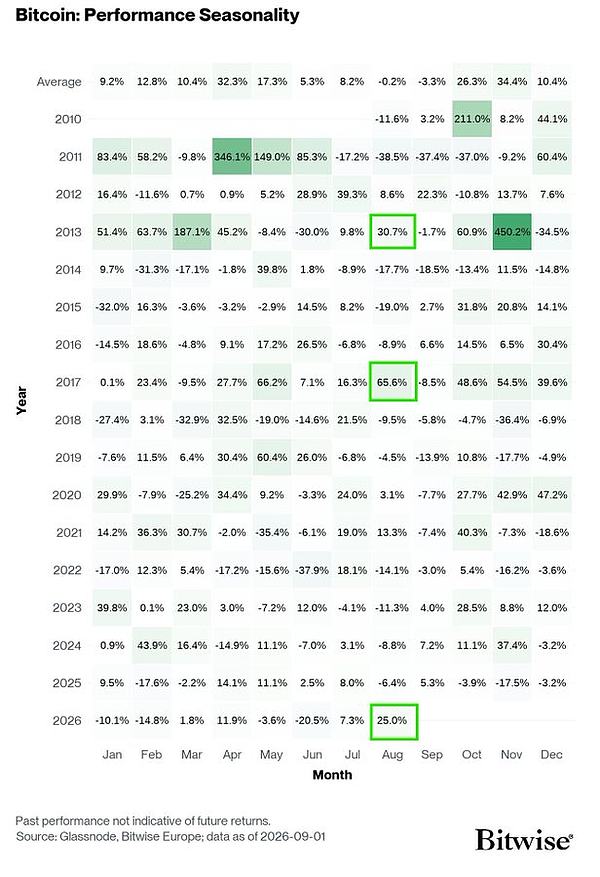
As of September 1st, when this article was written, Bitcoin had returned to around $77,000, and the August rebound has temporarily entered a period of consolidation.
So here's the question: The most "difficult" September in history has begun; can this market rally continue? Will the "September curse" repeat itself? Looking only at historical data, bulls should indeed be cautious. CoinGlass's long-term statistics show that September has consistently been one of the worst-performing months for Bitcoin, with a historical average return of approximately -3% to -4%. Particularly noteworthy is that in past years when August saw significant gains, September often saw profit-taking. Dow Jones Market Data statistics show that since 2014, September has been the worst-performing month for Bitcoin on average, with an average decline of approximately 2.2%. The problem is that seasonality is merely a statistical result, not a market law. The sample size is only a little over a decade, and today's Bitcoin market is vastly different from that of 2014 and 2017—the impact of spot ETFs, institutional funds, options, and macro liquidity on prices can no longer be explained by past cycles. Therefore, instead of worrying about whether the market will fall in September, it's better to consider: will the funding logic that drove the August surge continue to be effective?
Will Bitcoin reach $90,000 in September 2026?
Yes, no
Powered by Moment
Predict. Earn Points. Unlock the Airdrop
The real engine of August is "dollar credit transactions"
On August 19, the U.S. Treasury Department announced that, starting September 9, the single limit for long-term Treasury liquidity repurchase will be increased from at least $2 billion to at least $4 billion, at least doubling the size, and will continue until November 4. This event is significant because US long-term Treasury yields had been rising continuously, and financial conditions were becoming increasingly tight. The Treasury's expanded repurchase operations were interpreted by the market as a signal to suppress bond market pressure and improve liquidity. Bitcoin subsequently became one of the beneficiaries. Bitwise's latest September report argues that fiscal pressure is forcing US policymakers to intervene in financial conditions more frequently, and the release of funds from fiscal accounts may improve liquidity in the banking system. Meanwhile, the correlation between Bitcoin and gold has risen to a six-year high, and "currency devaluation trading" has returned to the center of the market. Wall Street is also reinforcing this logic. Bernstein analyst Gautam Chhugani believes that the 40-year cycle of declining long-term interest rates has ended, and rising government debt, concerns about currency purchasing power, and institutional adoption will continue to increase the attractiveness of scarce assets. He predicts that Bitcoin could re-reach $150,000 by mid-2027 and $300,000 around 2029. Geoff Kendrick, Head of Digital Asset Research at Standard Chartered Bank, also pointed out that the recent intervention of the US government in the bond market has reinforced the core investment logic behind Bitcoin's creation—hedging against the risks of fiat currency systems and government policy intervention. This is why August was not a simple "cryptocurrency rebound," but more like a macro-level trade. What are the real risks? However, things began to complicate in September. Federal Reserve Chairman Kevin Warsh clearly stated in his Jackson Hole speech at the end of August that US inflation data was more worrying than employment: the PCE year-on-year growth rate was still 3.7%, and the six-month annualized trend was even higher at 4.1%, significantly exceeding the 2% target. As of September 1st, with oil prices and global bond yields rising again, market expectations for a September rate hike by the Federal Reserve have clearly intensified. Reuters reported that market pricing that day indicated a probability of a September rate hike had risen to approximately 68%. The yield on the 10-year US Treasury note rose to 4.798% at one point. The next Fed meeting is scheduled for September 15th and 16th. This means that the biggest risk for Bitcoin in September is not the so-called "historical curse," but rather: If oil prices continue to rise, inflation resurfaces, US Treasury yields surge, and the Fed tightens policy again, then the liquidity trade seen in August could be reversed. It is worth noting that institutional funds have not completely withdrawn due to rising prices. In August, US spot Bitcoin ETFs saw a significant resurgence of net inflows, attracting funds for several consecutive days, reaching a total size of several billion dollars. Farside data shows that BlackRock's IBIT remains one of the primary sources of these funds. Bitwise, however, has found that on-chain structure has undergone changes more noteworthy than price. Their latest research shows that Bitcoin has regained several key on-chain cost lines, and both the long-term holder model and the "Risk-On Transition" model have shifted to a risk-averse state. Bitwise therefore believes that the market is signaling the start of a new bull market cycle. However, it also presents a threshold: $83,000. Bitwise points out that the $83,000 level is not only a significant technical resistance but also roughly corresponds to the average cost of capital for ETF investors. Only by truly stabilizing at this level can a new, higher high be formed, confirming a complete reversal of the previous downtrend. This could be the most important support level throughout September. Three possible scenarios for September: Decrypt analyst Jose Antonio Lanz outlines three directions. The first, and currently the most probable scenario, is a period of high-level consolidation followed by an attempt to break through. As long as the $73,000-$75,000 range is not decisively broken, ETF funds continue to flow in, and US Treasury yields do not spiral out of control, Bitcoin is likely to complete its turnover between $75,000 and $83,000, and then retest $83,000. Once it breaks through and holds above $83,000 with significant volume, the technical structure will improve significantly, and the market is likely to refocus on the $92,000-$100,000 range in the next phase. Jose's technical indicators consider $81,500-$82,500 as the first resistance level, while higher resistance is concentrated in the $92,000-$100,000 range. The second scenario is continued consolidation and market correction in September. August has already seen a 25% increase, resulting in substantial short-term profit-taking. Furthermore, the major event around September 16th involves the Federal Reserve meeting, so the market could potentially enter a large consolidation range around $70,000 to digest the overheated sentiment. The third scenario, and one that must be guarded against, is as follows: If oil prices continue to rise, the Federal Reserve confirms an interest rate hike, the yield on 10-year US Treasury bonds rises further, ETFs experience sustained net outflows, and Bitcoin falls below $73,000, then the August rally could transform from a "bull market reversal" back into a large-scale short-covering correction. Analysts predict the next important support level is around $68,900. In summary, $73,000-$75,000 is the bulls' defense line, while $83,000 is the dividing line between bull and bear markets. The Federal Reserve meeting on September 15-16 may determine the direction of the next round. If $83,000 is ultimately and effectively broken, then the historical "September curse" may once again fail, and the 25% rise in August will be proven to be the beginning of a new trend. Conversely, if yields continue to soar and liquidity tightens again, then September may still remind everyone: History becomes history because the market often likes to suddenly teach investors a lesson when they are most optimistic.


 Joy


