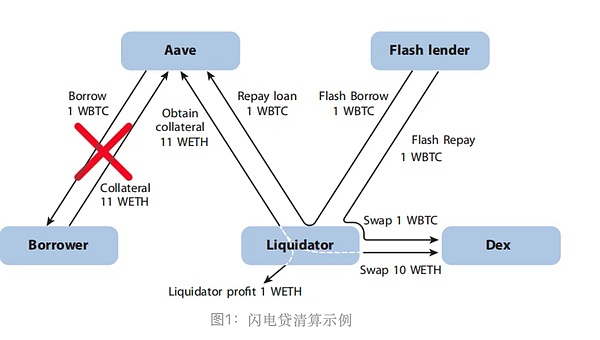
In 2026, Alfred Lehar and Christine A. Parlour published a review article, "Microstructure of Blockchain Cryptocurrency Markets." This article systematically examines the trading mechanisms, liquidity supply, price discovery, MEV (Mean Exchange Value Provider) mechanisms, and data risks of decentralized exchanges, pointing out that automated market makers (AMMs) have evolved from a stopgap measure under blockchain performance constraints into a significant innovation that may impact the structure of mainstream financial markets. The Fintech Research Institute of Renmin University of China has translated the core parts of this research. I. Introduction: From Smart Contracts to On-Chain Trading Smart contracts enable the direct trading of digital assets on the blockchain, giving rise to decentralized exchanges (DEXs). Early examples include Bancor, launched in 2017, and Uniswap, launched in 2018. Unlike exchanges that rely on centralized institutions for matching and custody, DEXs execute trades through public programs, with their core mechanism being automated market makers (AMMs). As of the time of writing, various DEXs had approximately $25 billion in liquidity across their AMMs, with daily trading volume roughly reaching this level. Understanding DEXs begins with understanding the institutional foundation of blockchain. The Ethereum Virtual Machine (EVM) can be viewed as a distributed computer maintained by global nodes. Transactions are written sequentially into blocks, and users pay gas fees using native cryptocurrency. Token ownership is typically recorded by contracts, but identical names do not necessarily indicate identical economic attributes: some stablecoins can be issued or frozen by specific addresses, some tokens are partially destroyed during transfers, and others offer interest payments. Blockchain also features atomic settlement, meaning a set of operations either all succeeds or all are rolled back. This makes flash loans possible: arbitrageurs can borrow without collateral, trade across markets, and repay funds in the same transaction, and the entire transaction will fail if any part of the process fails.
II. Liquidity Supply in Traditional Markets
Traditional financial markets are not only places for asset trading, but also markets where patient traders sell immediate transactions to those eager to complete them.immediacy ... In a limit order book (LOB), liquidity providers submit buy and sell limit orders and are compensated through the bid-ask spread. Because orders may be outdated by the time they are executed, market makers face adverse selection (or "picking-off risk") from informed traders using older quotes. The spread thus reflects not only the price of the trading service but also compensates for the information risk borne by the market maker. In traditional order books, liquidity providers compete for the best price; those who are at the top and have their orders filled receive the revenue, while those whose orders are not filled receive no income. This competition drives institutional investment in low-latency systems, hosting, and high-speed data, ultimately concentrating liquidity supply in the hands of a few specialized institutions. AMMs employ a different organizational structure: liquidity providers (LPs) within the same price range share the commission on a quota basis and also share adverse selection losses. This lowers the barrier to entry, theoretically allowing ordinary investors, pension funds, or endowments to contribute assets to the pool, but it does not eliminate risk or the value of professional management.
III. Decentralized Exchanges and Automated Market Makers
On-chain order books require separate gas fees for placing, modifying, and canceling orders, resulting in high costs in the early stages. This led to AMMs becoming the dominant mechanism. Taking Uniswap v2 as an example, each liquidity pool trades a pair of tokens. Limited partners (LPs) deposit the two assets in equal proportions, and traders exchange assets from the pool. Ignoring transaction fees, the reserves of the two assets satisfy the constant product formula x×y=k. Transactions change the reserve ratio and the price in the pool; the larger the order, the stronger the price impact; the deeper the liquidity pool, the smaller the impact of an equivalent transaction.
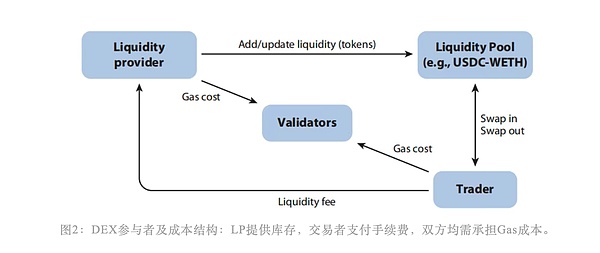
AMM contracts do not actively observe news or update valuations. When external market prices change, the old quotes are retained in the pool, and arbitrageurs will trade with the liquidity pool until the on-chain price reappears close to the market price. Therefore, early AMMs clearly separated liquidity supply from price discovery: LPs passively provide inventory and earn fees, while arbitrageurs profit by correcting mispricing. Fees are not risk-free returns. If the fee rate is zero, LPs only bear the cost of adverse selection; if the fee rate is too high, traders will turn to other markets.
IV.Price Discovery, Transaction Costs, and Market Efficiency
Ethereum generates a new block approximately every twelve seconds, therefore on-chain price updates are slower than those of centralized exchanges (CEXs) with continuous transactions. However, price discovery does not necessarily begin on CEXs. When decentralized lending protocols liquidate collateral, selling pressure may first form on DEXs before transmitting to centralized markets; under centralized liquidity mechanisms, LP adjustments to price ranges also contain information. Related research has found that price shocks on DEXs may be lower than in limit order markets, and passive liquidity is more stable during crises. Because gas costs are fixed, DEXs are not conducive to small transactions, but may provide lower overall costs for large transactions. AMMs may also be applied to foreign exchange and cross-border payments. Stablecoins and on-chain liquidity pools can connect to traditional money markets, but their efficiency still depends on the smoothness of arbitrage and the timely correlation between on-chain and off-chain prices. V. **Maximum Extractable Value and its Governance** Decentralized systems lack a reliable unified clock and cannot strictly implement the price-time priority of traditional markets. Users typically send transactions to a public mempool first. Block builders and validators can select transactions and determine the order. The revenue generated by the ordering is called the maximal extractable value (MEV). A typical sandwich attack involves a bot buying before the user buys, then selling after the user's order drives up the price, thus turning the user's price shock into its own profit. MEVs are not all harmful. Cross-market arbitrage can unify prices, and liquidating under-collateralized loans helps maintain the stability of lending agreements. Therefore, the focus of governance is not on completely eliminating bots, but on distinguishing between activities with social value and predatory front-running. Bulk trading, uniform transaction prices, virtual rates, private mempools, and auctioning back runaway rights with a portion of the profits returned to users are all market-based mitigation mechanisms. Just-in-time liquidity (JIT) also has two sides: while LPs can temporarily inject funds after seeing large orders, reducing the price impact of that transaction, it dilutes the fee income of long-term LPs and may weaken the supply of long-term liquidity.
On-chain tokens are the sole record of ownership; loss of private keys, misdirection to addresses, or incorrect contract calls are usually irreversible. CEXs primarily bear the risks of custody, fraud, and bankruptcy; DEXs themselves do not directly hold user assets, but the risks are transferred to token contracts, smart contract vulnerabilities, and user actions. Anyone can issue counterfeit assets using the same abbreviation as well-known tokens, thus the open listing mechanism may be abused.
Blockchain transparency cannot automatically eliminate wash trading: research has found a large amount of artificially inflated trading volume in Uniswap. Due to the significant differences in operational risks across different trading venues and assets, comparing only fees, spreads, or price shocks may underestimate the importance of security, recoverability, and legal protection.
VII. On-Chain Data and Research Challenges
DEX transactions, liquidity adjustments, and contract calls all leave on-chain records, providing highly granular data for studying market microstructure. However, public access does not equate to ease of use. Researchers typically need to parse event logs, identify economic behavior based on topic0, and reconstruct transaction and pool states from the protocol's creation. Different protocols, and even different versions of the same protocol, use different log formats; some protocols even reduce records to save on gas costs. Token decimal places, integer rounding, block reorganization, and contract upgrades can all cause measurement errors.
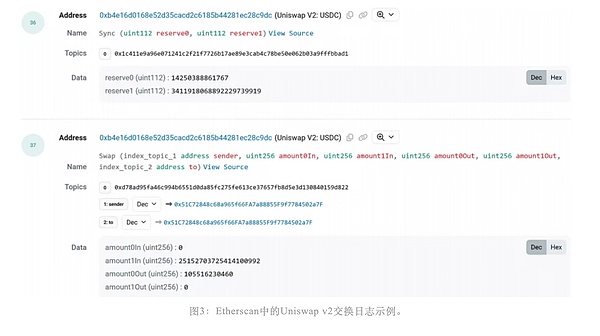
Block timestamps are not precise times in the traditional sense of exchanges. Multiple transactions within a block may have the same timestamp, but are executed in a fixed order; accurate time synchronization between different blockchains is even more difficult. DEX trading volumes also lack a unified standard; incomplete protocol coverage, different pricing assets, and extreme prices can all distort statistical results. Therefore, moving from "data visibility" to "being able to support reliable economic inferences" still requires protocol identification, data cleaning, and economic interpretation.
VII. Conclusion and Outlook
AMM (Area-of-Market Module) emerged from the technical constraints of low throughput and high order modification costs in early blockchains, yet it has become one of the most important innovations in trading mechanisms over the past decade. It demonstrates that limit order books are not the only effective market organization method and may provide lower price shocks, more stable liquidity, and lower costs for large transactions in certain scenarios. With the tokenization of real-world assets such as stocks, bonds, and money market funds, the importance of AMM may further increase.The article also emphasizes that existing research mainly focuses on a few protocols such as Uniswap, and on-chain data processing remains a significant hurdle for empirical research. Competition between protocols and networks will continue to cause fragmentation. DeFi is particularly worthy of study because many problems that traditional finance relies on regulation to solve are addressed in on-chain markets through the design of private protocols. Comparing the efficiency, distributive consequences, and security boundaries of these mechanisms not only helps in understanding the cryptocurrency market but may also provide new evidence for reforming trading systems in mainstream financial markets.

 Kikyo


