Author: Prathik Desai; Source: TokenDispatch; Compiled by: Shaw, Jinse Finance
Even when we see the "transaction successful" notification and hear the card swipe notification, at the moment of card payment, no funds are actually transferred to our bank account. At that instant, only one thing happens: the bank promises the merchant that it will subsequently clear the funds.
Banks charge a fee for building this trust layer, which guarantees the user's ability to fulfill payment obligations. From small shop owners allowing us to buy on credit to banks guaranteeing the payment behavior of thousands of businesses, the entire system is built on this layer of trust. It is one of the most valuable components of the financial system, yet it is also the least visible.
Without this layer of trust, no business activity or financial system can function. I discussed this point last week: many companies are building the foundation of trust and identity for machine-to-machine transactions in the intelligent agent economy. Crypto infrastructure paired with stablecoins eliminates intermediaries in the monetary system, whether it's asset storage, fund transfers, or compound interest growth. Crypto payment cards now exist, allowing us to pay for daily expenses using digital assets. These new payment methods also require guarantees of the wallet holder's ability to fulfill payment obligations. However, crypto payments are cleared much faster than traditional bank card payments, so we need a more efficient authentication and guarantee mechanism to ensure wallet holders have the ability to settle payments. This article will discuss this topic.
The Operating Mechanism of Bank Card Payment
Breaking down the complete process of a bank card payment reveals five main participants and a trust endorsement process. These are: you as the buyer, the merchant (seller), the merchant's issuing bank, the card network infrastructure (Visa or Mastercard), and your issuing bank (card issuer).
Where Does Value Flow?
Tracing the flow of funds throughout the entire process reveals that profits bypass all homogenized business segments. Stablecoin issuers cannot profit from the payment card business chain.
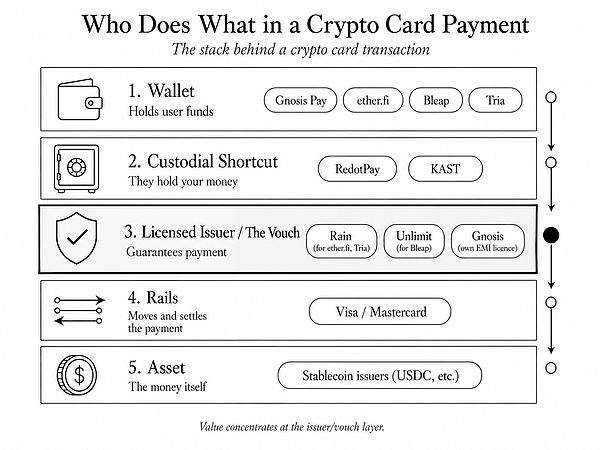
Wallets control user traffic entry points, but all underlying capabilities need to be leased out, including licenses, transaction guarantees, and clearing services. This limits the profit margin that wallet companies can obtain from guarantee and authentication services.
The real value flows to licensed institutions, which undertake this laborious, high-risk, and heavily regulated work of guaranteeing and verifying transactions. This business allows no room for error. Rain holds card organization membership, handles stablecoin clearing, and provides substantial transaction guarantees for projects like Ether.fi and Tria. As an infrastructure service provider, Rain's post-funding valuation is close to $2 billion, higher than the valuations of many applications built on it (Bleap, Ether.fi, Tria). Above all players, established giants still hold a dominant position. Visa handles stablecoin clearing transactions worth billions of dollars annually; the profit margin per transaction may seem small, but with massive transaction volumes, the returns accumulate rapidly. Whenever crypto and fintech merge, this pattern emerges: value doesn't accumulate in front-end applications but rather converges at the infrastructure layer. The formation of irreplaceable and non-homogeneous capabilities occurs at this layer, requiring developers to provide specialized solutions to address existing or emerging problems. The traditional banking system's slow clearing speed stems from banks transferring funds through a series of intermediaries, processing them in batches overnight. However, this slow process has an advantage: in case of erroneous payments or consumers not receiving the corresponding goods or services, users can initiate a chargeback. Since payments are controlled by the bank, after thorough verification, the bank can cancel the transaction at any time. The crypto industry has achieved high-speed clearing, but transactions are irreversible, sacrificing risk control mechanisms in exchange for speed. Increased clearing speed also further amplifies the value of guarantee and authentication services. Guarantees must be completed instantly and are more susceptible to malfunctions and various risks, thus requiring well-capitalized licensed institutions. By accelerating and reducing costs, the crypto industry has turned the clearing layer into a highly homogenized, standardized process, but at the same time, it has created greater value capture opportunities in the guarantee and authentication layer. Participants who can combine the scarce capability of instant guarantees with a self-custody model will reap the greatest value. Rain and RedotPay are moving towards this goal from two diametrically opposed directions. Rain, holding licenses, clearing liquidity, and guarantee capabilities, exports this infrastructure to all other participants and profits from it. RedotPay, on the other hand, has completely abandoned self-custody, with the platform directly managing user funds, betting on its traffic distribution advantage. The platform understands that most users care more about a smooth transaction experience than asset custody; therefore, it leverages this by charging users for a low-friction experience and a user-friendly interface that facilitates fund transfers and asset management. Every round of financial technology innovation claims to eliminate intermediaries. However, each innovation inevitably creates new business pain points, attracting more participants who seek to capture the value generated by solving these pain points. In the payment card ecosystem, this pain point is concentrated at the guarantee and authentication layer. Whoever can eliminate the pain points in this process will reap the substantial profits that were previously accumulated there.


 Anais

