Tellor's Decentralized Oracle Protocol Revolutionizes Blockchain Data Access
Tellor transforms blockchain data handling with security, decentralization, and upcoming innovations.
 Brian


Author: Minara Chinese Source: X, @MinaraCN
Over the past week, we analyzed 43,618 Hyperliquid addresses to answer one question: What trading methods do truly profitable accounts most frequently use?
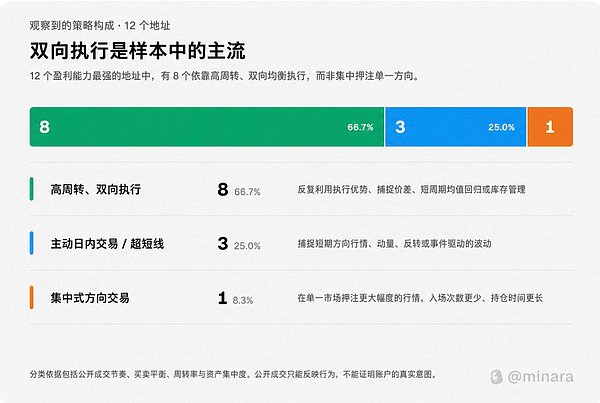
The answer isn't "betting on a coin earlier." In further research on 12 top-performing accounts, the most common strategy was one emphasizing execution. Eight accounts exhibited high turnover and two-way trading characteristics; three resembled active day traders or scalpers; and only one was a concentrated directional trader.
What's truly worth observing is how addresses enter and exit the market: trading rhythm, buy-sell balance, capital turnover, position concentration, market selection, and how much profit is generated per unit of risk taken during repeated capital turnover.
What's really worth observing is how addresses enter and exit the market: trading rhythm, buy-sell balance, capital turnover, position concentration, market selection, and how much profit is generated per unit of risk taken during repeated capital turnover.
How to filter out 1,681 profitable accounts from 43,618 addresses? The filtering process involves five steps. 1. Compile complete leaderboard data. We loaded all 43,618 records from the CSV file, including address, ranking, nickname, account value, and daily, weekly, monthly, and historical cumulative PnL, ROI, and trading volume. Using complete data avoids selecting expected cases from a small sample.
2. Excluding Distorted Small Samples
Selected accounts must simultaneously meet the following conditions: account value not less than $10,000; historical cumulative PnL and ROI both positive; cumulative trading volume of at least $1 million; monthly trading volume of at least $100,000. This excludes accounts with too small a principal but abnormally high ROI, accounts that have been inactive for a long time, and accounts that rely solely on a single trade for profit.
3. Checking if Profitability Continues to the Recent Period
We compared the account's PnL and ROI across four timeframes: 1 day, 1 week, 1 month, and historical cumulative, focusing on weekly and monthly performance. Having one successful trade in the past is not sufficient; if the account has not been profitable recently, it will not receive a high score.
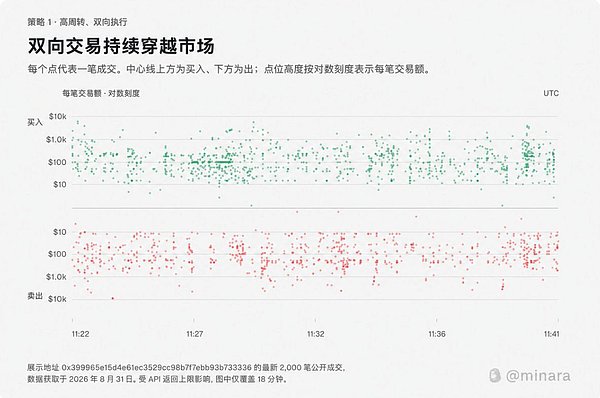
0x399965e15d4e61ec3529cc98b7f7ebb93b733336 is the fastest example. The 2,000 trades returned by the API only covered approximately 20 minutes, with a median interval between adjacent trades of 0.21 seconds. Buy orders accounted for 49.85%, and sell orders accounted for 50.15%. This interval generated a net closed-out profit of $2,187 on a trading volume of $1.44 million, equivalent to 0.152%.
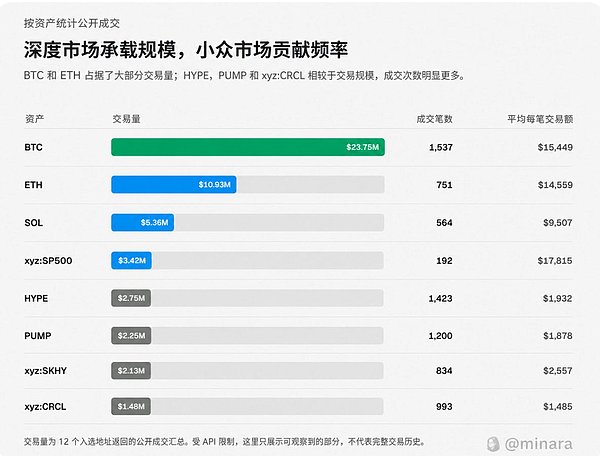
BTC Transaction Volume: $23.75M Sample Transaction Count: 1,537 Average Transaction Amount: $15,449
ETH Transaction Volume: $10.93M Sample Transaction Count: 751 Average Transaction Amount: $14,559
SOL Transaction Volume: $5.36M Sample Transaction Count: 564 Average Transaction Amount: $9,507
xyz:SP500 Trading Volume: $3.42M Sample Transaction Count: 192 Average Transaction Amount: $17,815
HYPE Trading Volume: $2.75M Sample Transaction Count: 1,423 Average Transaction Amount: $1,932
PUMP Trading Volume: $2.25M Sample Transaction Count: 1,200 Average Transaction Amount: $1,878
xyz:SKHY Trading Volume: $2.13M Sample Transaction Count: 834 Average Transaction Amount: $2,557
xyz:CRCL Trading Volume: $1.48M Sample Transaction Count: 993 Average Transaction Amount: $1,485 The differences are very significant. The average transaction size for BTC is approximately 8 times that of HYPE; xyz:SP500 has the highest average transaction size in the table, while xyz:CRCL is in the lowest tier. In the high-turnover two-way group, the sample transaction volume for BTC is $21.66 million. ETH, xyz:SP500, HYPE, xyz:SKHY, and xyz:CRCL form the second tier. These addresses appear to hold larger positions in deeply liquid markets and then seek more intensive execution opportunities in smaller markets. The intraday trading group is more concentrated on ETH, SOL, PUMP, BTC, and DOGE. This asset portfolio aligns better with strategies that chase short-term directional fluctuations and volatility, rather than simply pursuing market depth. The conclusion isn't that "profitable accounts prefer BTC," but rather that asset selection itself is part of the strategy design. High-turnover strategies require liquidity, ultra-short-term strategies require sufficient volatility, and centralized directional strategies require a clear judgment of a particular market. What is truly replicable is the trading method, not a single trading action. The 12 addresses did not have a consistent judgment on market direction, traded different assets, and used different time scales. What truly differentiates them is the way profits are generated. The two-way group turned over $51.37 million within the sample period, earning approximately 0.305%. They relied on small, repeatable, and execution-related advantages. The intraday group experienced more pronounced directional shifts, and its short-term results were less volatile. The last address concentrates risk in a single market while waiting for market movements. Therefore, the most common strategy among these profitable addresses cannot be simply categorized as "high frequency." More accurately, they achieve this through high turnover and two-way execution, controlling inventory risk while repeatedly realizing small advantages many times. This also explains why simply copying the latest positions of a particular address often fails to yield truly useful information. Positions are merely the result of a trading system at a given moment. The strategy itself is embedded in trading rhythm, buy-sell balance, position size, market selection, capital turnover, and risk management.
Tellor transforms blockchain data handling with security, decentralization, and upcoming innovations.
BrianTellor Tributes (TRB) experienced a remarkable 2000% surge in Q4 2023, reaching new ATHs before facing a dramatic fall due to market manipulation, underscoring the volatile nature of the crypto market.
 Alex
Meme coins like $TSUKA show volatile gains but high risks, emphasizing the importance of timing in investments. Sponge v2, building on past successes, aims to merge meme status with sustainable utility, targeting mainstream adoption.
 Joy
Reported by Econovill, Hashed's strategic focus centers on early-stage ventures aiming to expand their user base by enhancing blockchain infrastructure and integrating content and intellectual property rights (IP).
 Edmund
HSBC Hong Kong ramps up digital currency initiatives for cross-border payments, while regulatory bodies signal openness to cryptocurrency exposure. This marks a notable advancement in the region's financial landscape.
JoyDuring this period, the government amassed a total of 78.6 million soms, nearly $883,000, during the first 11 months of the year.
AlexUsers that encounter a "blocked" message on the website are to note that the team is actively addressing the issue. The platform anticipates a prompt recovery once traffic normalises.
AlexBitcoin's surge to $45,000 triggers record-high 66% funding rates in perpetual futures, making long positions costly. Market experts predict sustained bullishness amid expectations for a Bitcoin ETF approval.
JoyxKingdom combines SocialFi and GameFi, offering kingdom building, hero upgrades, Twitter rewards, and a multifaceted earning ecosystem.
BrianThree promising early-stage GameFi projects: one quietly launched with $6M funding, another offering testnet airdrops and FreeMints, and a third preparing a limited 500 FreeMint release.
 Kikyo