Author: AJC, Research Manager, Blockworks Research; Translator: Jia Huan, ChainCatcher
Key Takeaways
While Robinhood's overall business continues to reach new highs, its crypto business is declining. In the second quarter of 2026, crypto revenue fell 38% year-over-year to $100 million, representing only 8% of the company's total revenue; retail crypto transaction volume fell 36% year-over-year; and crypto assets as a percentage of Robinhood's total custodied assets also fell to a record low of 7%.
Robinhood Chain achieved one of the strongest L2 launch results in recent years. In July, the network generated $3.6 million in Real Economic Value (REV), representing 38% of all L2 chain revenue tracked by growthepie, surpassing established networks such as Polygon and Base.
The main driving force behind Robinhood Chain's early activity was not RWA, but Meme Coin.
In July, Memecoin accounted for 51% of spot trading volume, while RWA accounted for only 5%. Meanwhile, 48% of RWA trading volume came from liquidity pools comprised of RWA and Memecoin. Robinhood's most definite monetization opportunities actually lie above the infrastructure layer. USDG is currently projected to generate $10.5 million in annualized interest income, while Morpho has demonstrated the distribution value of direct integration into the Robinhood main app. In contrast, Lighter, which only integrates with Robinhood Wallet, generates only 0.2% of its total perpetual contract trading volume through Robinhood deployments. Robinhood Chain is currently insufficient to have a substantial impact on Robinhood's overall performance. Known revenue sources currently total approximately $54.8 million annualized, equivalent to 14% of Robinhood's annualized crypto revenue. If Robinhood Chain wants to truly become a significant business, Robinhood needs to scale USDG, monetize its main app's user entry point, or use Robinhood Chain as a funnel for users to access other high-value products. Introduction: Robinhood's Crypto Business at a Crossroads Perhaps no company represents the rise of retail investors better than Robinhood. Robinhood has almost become synonymous with retail investment, and its business has expanded rapidly as a result. Can Robinhood Chain become a new growth engine for Robinhood? In the second quarter of 2026, Robinhood's quarterly revenue reached a record high of $1.31 billion, a 32% year-over-year increase and a 92% increase compared to the second quarter of 2024. The growth is driven not only by core trading businesses like stocks and options, but also by a continuously expanding product portfolio. Currently, Robinhood has 13 business lines with annualized revenue exceeding $100 million. In fact, all trading revenue lines achieved double-digit year-over-year growth in the second quarter, with one exception: cryptocurrency. Crypto once accounted for more than a third of Robinhood's total revenue, but now it has become negligible. In the second quarter of 2026, only 8% of Robinhood's quarterly revenue came from cryptocurrency, the lowest level since the third quarter of 2023. Crypto's share of Robinhood's revenue has become so low that its event contracts business, launched only last year, surpassed cryptocurrency revenue in the second quarter, with the former generating $156 million and the latter $100 million. The problem isn't just the declining share of crypto in Robinhood's revenue. Overall, Robinhood's core user base is showing waning interest in cryptocurrency. While the reasons for this phenomenon are not unique to Robinhood, the decline is still astonishing.
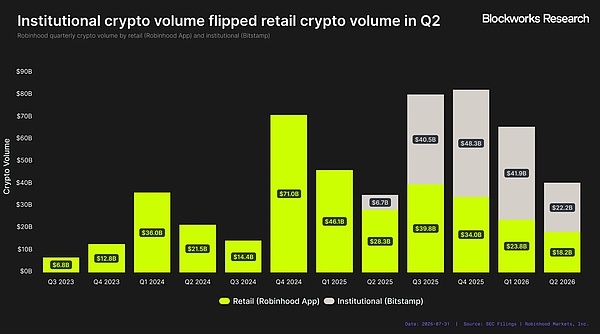
Transaction activity best illustrates this point. In the second quarter of 2026, retail crypto transaction volume within the Robinhood App was only $18.2 billion, a 36% year-over-year decrease, the lowest quarterly level since the third quarter of 2024. The decline was so significant that institutional transaction volume completed through Bitstamp surpassed Robinhood's retail transaction volume for the first time.
But institutional transaction volume was also far from strong. Bitstamp's transaction volume for the quarter was $22.2 billion, its second-lowest quarterly level in history.
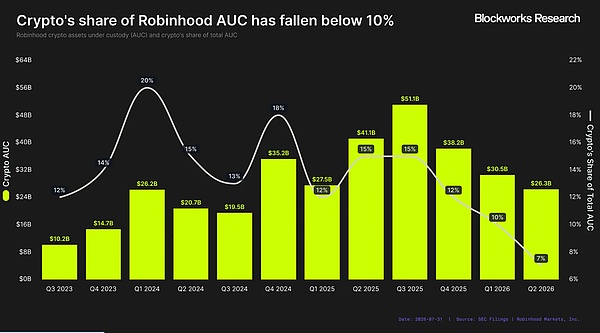
Transaction volume isn't the only crypto metric showing weakness for Robinhood. In the first quarter of 2024, Robinhood's crypto assets under custody totaled $26.2 billion, representing 20% of the company's total assets under custody. More than two years later, the size of crypto assets has remained largely unchanged at $26.3 billion, but its share of Robinhood's total assets under custody has fallen to 7%, a record low for a quarter.
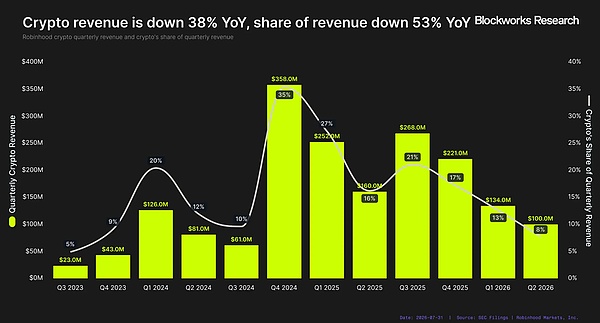
In this context, Robinhood's crypto revenue is naturally affected.
In this context, Robinhood's crypto revenue is naturally affected.
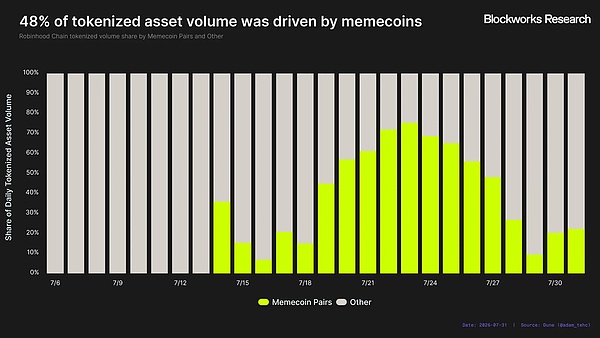
Moreover, the actual impact of Meme Coin on Robinhood Chain trading activities may be even higher than this figure.
Taking RWA as an example, the Meme Coin issuance platform LONG() promoted a strategy that pools Meme Coin with tokenized stocks or ETFs, thereby binding the price movement of Meme Coin to the underlying RWA.
For example, if the underlying RWA rises by 5%, even if no one buys or sells Meme Coin, the price of Meme Coin will also rise by 5%. Therefore, what appears to be a portion of RWA trading volume is actually driven by Meme Coin as well.
From July 6th to July 31st, 48% of RWA trading volume came from liquidity pools paired with Meme Coin and RWA. Meme Coin can indeed be a powerful source of chain revenue, but historically, it has rarely been sustained in the long term. Meme Coin activity is highly volatile; Ethereum, Avalanche, TRON, and Base have all experienced periods of extremely active speculative activity before funds and trading moved elsewhere. Robinhood Chain might be able to retain this activity, but one month's data is clearly insufficient to draw conclusions. It remains uncertain whether Meme Coin can become a sustainable source of REV for Robinhood Chain, or whether Robinhood Chain is simply the latest stop in this round of fund rotation, with funds ultimately returning to Solana. Looking at the bigger picture, it's unlikely that Robinhood's crypto business will be revived solely through Robinhood Chain's REV. Network revenue across the entire industry is experiencing a structural decline. For first-generation smart contract platforms, blockchain space was once a highly profitable business. However, as blockchain space has become increasingly commoditized, it has become increasingly difficult for new chains to generate large-scale revenue through transaction fees. In July, the blockchains tracked by Blockworks generated a total of $122.4 million in network revenue, the lowest monthly level in three and a half years. In comparison, network revenue in July 2025 was $333.7 million, a year-on-year decrease of 63%. Moreover, this decline cannot be entirely attributed to the current market environment. In July 2023, during the previous bear market, the various chains were still able to generate $300.1 million in network revenue. As mentioned earlier, Robinhood already has 13 business lines with annualized revenue exceeding $100 million. It's hard to imagine Robinhood Chain joining this ranks solely through network revenue. Even if Robinhood continues to expand its share in L2 activity, chain revenue will ultimately be limited by the overall market size, with an annualized revenue cap of approximately $100 million. To break through this cap, Robinhood must bring its existing user base onto the chain. However, Robinhood's users are primarily located in the United States, and under the current regulatory environment, most of them cannot directly use Robinhood Chain through the Robinhood App, so this process is likely to take time. If Robinhood hopes that Robinhood Chain will become the next business line with annual revenue exceeding $100 million in the short term, it must find monetization methods beyond network revenue. Application Layer Commercialization The focus of monetization in the crypto industry is gradually shifting from the infrastructure layer to the application layer. Solana is a good example.
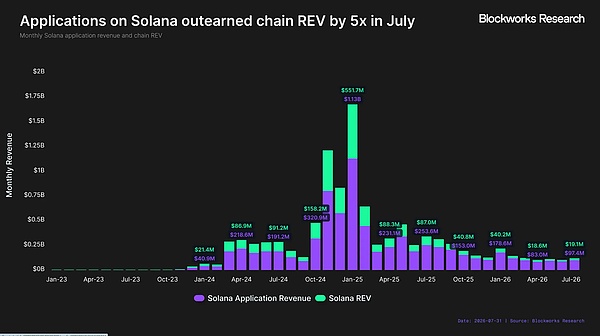
In January 2024, when Solana began its recovery, Solana applications generated a total of $40.9 million in revenue that month, while the Solana network itself generated $21.4 million in REV, a ratio of 1.9 times.
By January 2025, at the peak of the Solana bull market, application revenue reached $1.13 billion, while Solana REV was $551.7 million, maintaining a ratio of approximately 2 times.
However, the gap between the two widened rapidly thereafter. By July 2026, for every $5 in revenue generated by Solana applications, the underlying network only received $1 in REV.
From a broader perspective, applications are capturing an increasingly larger share of value creation, while the underlying blockchain is capturing a smaller and smaller proportion. [Image: Can Robinhood Chain become Robinhood's new growth engine?] If Robinhood hopes that Robinhood Chain will become its next business line generating over $100 million in annual revenue, it must directly participate in the commercialization of on-chain applications. Robinhood has not officially announced this as its strategy, but current actions point in this direction. The most obvious example is Robinhood's stablecoin strategy. Unlike most blockchains that rely on Circle's USDC or Tether's USDT as their primary stablecoins, Robinhood chose USDG as the native stablecoin for Robinhood Chain. This gives Robinhood an additional source of revenue: interest income generated from USDG's reserve assets. As of the end of July, the market capitalization of USDG on the Robinhood Chain reached $333.1 million. Assuming a 3.5% yield on the underlying reserve assets, with 90% of the related interest income going to Robinhood, USDG could generate approximately $10.5 million in revenue for Robinhood annually. Expanding the USDG supply further should not be difficult for Robinhood, and could establish a more stable revenue stream. If the USDG supply reaches $1 billion, a reasonable target, given that 11 blockchains already have at least $1 billion in stablecoin supply, USDG could generate $31.5 million in revenue annually, almost equivalent to Robinhood Chain's current chain revenue. Besides stablecoin integration, Robinhood Chain also appears to be seeking other revenue streams at the application layer. Lighter has already deployed a customized perpetual contract DEX on the Robinhood Chain and will share transaction fees with Robinhood on a 50/50 basis. As part of the partnership, Robinhood Wallet, a self-custodied wallet independent of the main Robinhood app, will offer Lighter perpetual contract trading directly within the app. Additionally, it's rumored that Morpho also paid for access to the Robinhood app. This is significantly different from the common industry model. Typically, blockchains incentivize applications to deploy to their networks, rather than applications paying the companies behind the blockchain. How much is Robinhood's distribution capability actually worth? The success of this entire application-layer strategy ultimately depends on the value of Robinhood's distribution capability. If the protocol is willing to pay for access to Robinhood users, then Robinhood can monetize its user base. Based on current cases, protocols on the Robinhood Chain can primarily distribute Robinhood users through two channels: ... On July 8th, daily transaction volume peaked at $11 million, but subsequently declined steadily, averaging only $2.1 million per day by the last week of the month. In July, Robinhood Wallet averaged slightly fewer than 7,000 active wallets per day. It's important to note that this analysis did not filter for Sybil addresses, so the actual number of unique users may be even lower. Compared to the broader ecosystem of wallets and trading applications on the Robinhood Chain, Robinhood Wallet remains a relatively small player. In July, the tracked wallets and trading applications generated a total of $3.08 billion in transaction volume, of which Robinhood Wallet accounted for only $119.6 million, representing a market share of less than 4%.
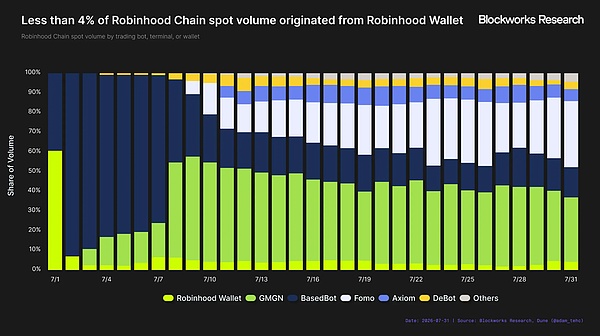
However, the transaction volume of these applications is largely driven by high-frequency and professional users. Robinhood Wallet ranks fourth among the tracked applications in terms of daily active wallets, but only sixth in terms of transaction volume.
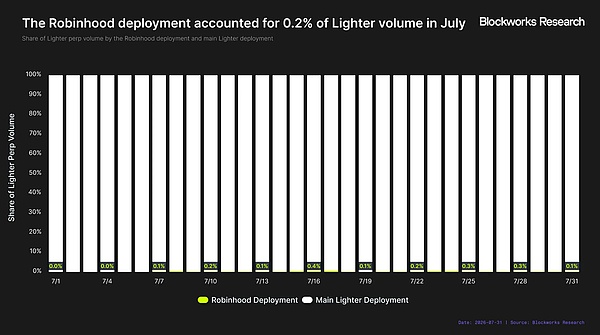
The integration of Lighter further demonstrates the limitations of Robinhood Wallet's distribution capabilities.
Since integrating with Robinhood Wallet, Lighter's deployment on Robinhood has only contributed 0.2% of its total perpetual contract transaction volume. In July, this trading volume was $86.8 million, even lower than the spot trading volume generated through Robinhood Wallet that month. More noteworthy is that Lighter is also directly incentivizing Robinhood Wallet users to trade perpetual contracts through token rewards. Lighter provided 11 million LIT tokens for this purpose, currently worth approximately $25 million. In other words, the already limited trading volume is still driven by incentives. Without these rewards, the actual trading volume would likely be even lower. Currently, it's difficult to believe that simply gaining access to Robinhood Wallet's distribution channels will bring significant value to the protocol. Robinhood Wallet's distribution capabilities may be limited, but the Robinhood main app is clearly not. Morpho is the most obvious example. Robinhood users can directly deposit stablecoins into Morpho through the main app and receive an incentivized 7% APY. As of the end of July, Morpho's deployment on the Robinhood Chain accounted for 5% of all Morpho deposits and contributed nearly 6% of lending. Just one month after its launch, the Robinhood Chain became Morpho's third-largest deployment network by TVL (TVL). It must be acknowledged that this TVL was also incentivized. Even so, the difference in distribution effectiveness between the Robinhood main app and Robinhood Wallet remains significant. While this isn't a direct comparison, the proportion of Robinhood Chain in Morpho deposits is 25 times the proportion of Robinhood's Lighter perpetual contract trading volume. Therefore, initial assessments of Robinhood's distribution capabilities are clearly polarized. For protocols that can directly access the Robinhood main app, this distribution capability seems extremely valuable. However, distribution solely through the Robinhood Wallet is far less appealing. Unless access to the Robinhood Wallet becomes a springboard to the main app in the future, it's difficult to understand why a protocol would be willing to sacrifice significant economic benefits just to gain user access to the Robinhood Wallet. Of course, this conclusion is currently based on only two early cases. Robinhood has not officially stated that application-layer distribution transactions will become a broader strategy for the company, nor is it clear to what extent the company intends to promote this model. But at least for now, the difference between the two is already very obvious. The true value of Robinhood's distribution capability lies not only in associating projects with the Robinhood brand, nor simply in deploying on the Robinhood Chain, but in its ability to directly reach users of the Robinhood main app.
Conclusion
This report begins with a core question: Can Robinhood Chain make crypto a significant driver of Robinhood's growth again?
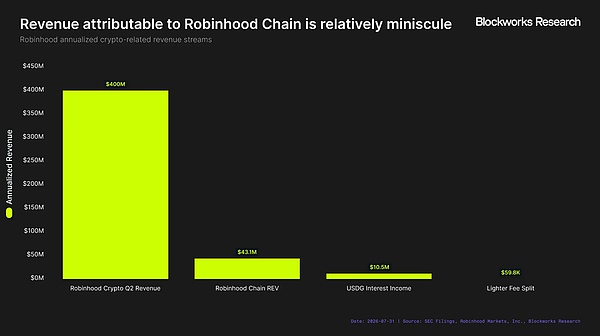
Early data has provided a fairly clear answer.
As a blockchain, Robinhood Chain's launch has been very successful, but it has not yet become a substantial revenue source for Robinhood's business.
Robinhood's crypto revenue in the second quarter was $100 million, equivalent to $400 million annualized.
Robinhood's crypto revenue in the second quarter was $100 million, equivalent to $400 million annualized.
In comparison, the quantifiable revenue streams for Robinhood Chain, including Chain REV, USDG interest income, and Robinhood's share of Lighter fees, total only $54.8 million annually, roughly equivalent to 14% of Robinhood's annualized crypto revenue. Of course, this comparison simply annualizes data from Robinhood Chain's first month and should not be considered its long-term revenue potential. The conclusion is clear: network revenue alone will never be sufficient to substantially impact Robinhood's performance. Block space has become too commoditized, and the overall L2 revenue market is too small. If Robinhood Chain wants crypto business to become a significant driver of Robinhood's growth again, the company must generate revenue from economic activities above the infrastructure layer. Stablecoins are currently the clearest path. Tether and Circle have demonstrated that interest income generated from stablecoin reserve assets can be a highly profitable business. Based on a 3.5% yield, if Robinhood retains all related interest income, every $1 billion increase in USDG supply could generate $35 million in annualized revenue for Robinhood. If the supply reaches $10 billion, this figure would grow to $350 million annually, almost matching Robinhood's current total annualized revenue from its entire crypto business. This obviously won't happen anytime soon, but given Robinhood's business scale and user base, this goal isn't unimaginable. Application distribution is another very attractive opportunity. Robinhood possesses something almost every other blockchain lacks: the ability to directly reach a large retail investor base. If the protocol is willing to pay integration fees to reach these users or share revenue with Robinhood, then Robinhood could commercialize its distribution capabilities without relying entirely on transaction fees generated by the blockchain itself. Early results indicate that this model is effective when the protocol can be directly integrated into the Robinhood main app. In contrast, the distribution value provided by Robinhood Wallet itself is much more limited. Another possibility is that Robinhood never intended to measure Robinhood Chain as a standalone, profitable business line from the outset. Robinhood Chain could also serve as a user funnel. It first attracts users to the on-chain world through tokenized assets, and then brings these users into the broader Robinhood ecosystem, allowing them to trade stocks, options, cryptocurrencies, and other financial products. In this model, the value of Robinhood Chain may not be directly reflected in network revenue, but rather in higher user activity and revenue from other Robinhood businesses. Currently, the answer to the question posed at the beginning of the report remains no. Robinhood Chain has not yet become a significant driver of Robinhood's growth, and network revenue alone can never achieve this. If this answer is to become yes in the future, Robinhood needs to expand the scale of USDG and monetize the user entry point of the Robinhood main app through application-layer distribution partnerships. Otherwise, the financial value of Robinhood Chain will likely be primarily reflected indirectly, serving as an entry point to direct users to higher-value financial products that already support Robinhood's business.


 JinseFinance